Polyvinyl Chloride (PVC) Market Share and Revenue Forecast Analysis – Report by MMR
Polyvinyl Chloride (PVC) Market to Reach USD 94.02 Billion by 2032, Driven by Construction, Infrastructure Development, and Material Innovation
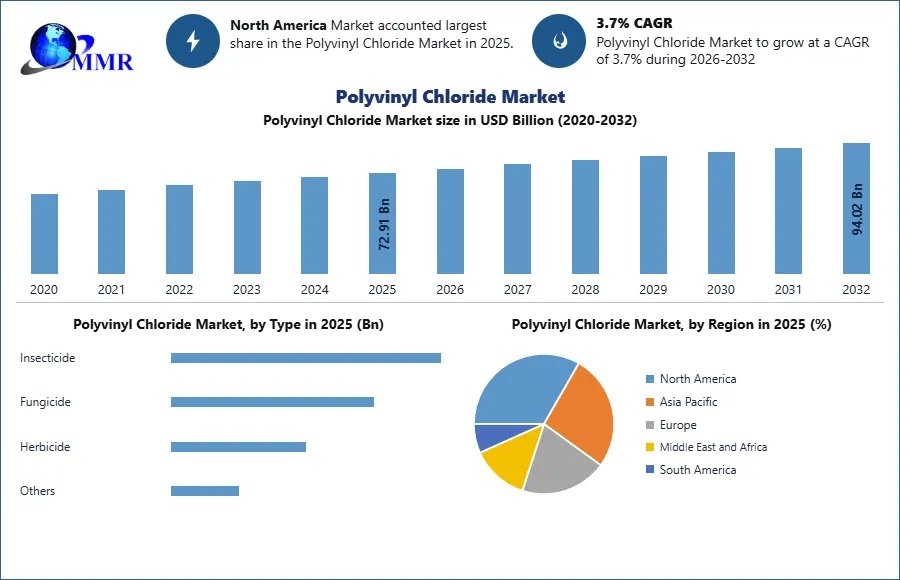
The Polyvinyl Chloride (PVC) Market is witnessing steady growth, supported by increasing demand for durable, cost-effective, and versatile materials across construction, infrastructure, automotive, electrical, and packaging applications. According to Maximize Market Research, the market was valued at USD 72.91 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 3.7% from 2025 to 2032, reaching nearly USD 94.02 billion by 2032. Growing investments in water supply networks, residential construction, urban development, and energy infrastructure are expected to create significant opportunities for PVC manufacturers worldwide.
Market Estimation, Growth Drivers, and Opportunities
PVC is one of the most widely used synthetic polymers because of its durability, chemical resistance, electrical insulation properties, low maintenance requirements, and adaptability to rigid and flexible applications. These characteristics make it an important material for pipes, fittings, window profiles, flooring, cable insulation, medical products, and protective coatings.
Infrastructure expansion remains a major growth driver. Governments and private developers are investing in water distribution, wastewater treatment, drainage systems, housing, and commercial buildings, increasing demand for PVC pipes and profiles. The material's resistance to corrosion and relatively low installation costs make it attractive for long-term infrastructure projects.
The transition toward energy-efficient buildings and the modernization of electrical networks also support market growth. PVC is widely used in insulation for electrical wires and cables, while its versatility enables manufacturers to develop specialized formulations for different industrial requirements.
Emerging opportunities include recycled PVC, bio-attributed feedstocks, improved plasticizer technologies, and advanced recycling processes. Manufacturers are increasingly exploring circular-economy strategies to reduce waste, improve resource efficiency, and meet sustainability expectations. However, volatility in feedstock prices, environmental concerns regarding chlorine-based materials, and increasingly stringent waste-management requirements may challenge market participants.
Get Your Free Sample Report Link : https://www.maximizemarketresearch.com/request-sample/23367/
United States Market: Latest Trends and Investment in 2025
In 2025, the US PVC market continued to benefit from infrastructure modernization, housing requirements, utility upgrades, and investment in domestic manufacturing. Federal infrastructure programs, including the Infrastructure Investment and Jobs Act, continued to support projects involving water systems, transportation infrastructure, and public utilities. These initiatives create potential demand for PVC pipes, conduits, and cable insulation. Industry attention also focused on manufacturing efficiency, supply-chain resilience, recycling technologies, and lower-impact polymer production. Chemical producers continued evaluating capital allocation, operational competitiveness, and sustainability initiatives amid changing feedstock economics and global trade conditions. Although individual investment decisions vary by company, the combination of infrastructure spending and demand for durable construction materials supports the longer-term outlook for PVC in the United States. Housing affordability pressures, interest rates, and regulatory requirements remain important factors influencing construction activity and future consumption.
Market Segmentation: Leading Segments
The PVC market is segmented by product type, stabilizer type, application, and end-user industry. Among product types, rigid PVC holds the leading position because of its extensive use in construction materials, water pipes, fittings, doors, and window profiles. Its strength, dimensional stability, weather resistance, and relatively low maintenance requirements make it suitable for long-term infrastructure applications.
By application, pipes and fittings represent a major demand category, supported by water distribution, sewage management, irrigation, and drainage projects. By end-user industry, building and construction is the dominant segment, reflecting the material's widespread use in residential, commercial, and industrial developments. These applications are expected to remain important contributors to global PVC consumption throughout the forecast period.
Competitive Analysis: Top Five Companies
The global PVC industry features established chemical manufacturers competing through production capacity, integrated supply chains, product quality, cost efficiency, and technological development. The following companies are important global competitors; their inclusion does not represent a verified ranking by individual market share.
- Shin-Etsu Chemical Co., Ltd.
Shin-Etsu Chemical is a leading global PVC producer with substantial manufacturing capabilities. Its competitive strengths include operational efficiency, product consistency, and integrated chemical production. Continued investment in manufacturing technology, quality management, and production optimization can help improve supply reliability and meet demand from construction and industrial customers.
- Westlake Corporation
Westlake manufactures PVC and related chlorovinyl products for construction, infrastructure, and industrial markets. Its vertically integrated operations provide advantages in managing raw materials and production costs. The company's 2025 investor communications highlighted the importance of favorable long-term supply-demand fundamentals for PVC and chlor-alkali products, supported by housing and infrastructure demand. Its focus on operational performance and disciplined investment can strengthen competitiveness.
- Formosa Plastics Corporation
Formosa Plastics is a major producer of PVC and other petrochemical materials. Its manufacturing scale and international customer base support its position in the global market. Production efficiency, process improvements, and the development of products for demanding industrial applications remain important competitive priorities. Investments in manufacturing reliability and resource efficiency can help the company respond to changing market requirements.
- INEOS Group
INEOS participates in the PVC industry through its INOVYN business, supplying suspension PVC, emulsion PVC, and specialty vinyl products. The company serves construction and industrial applications requiring consistent material performance. Its European manufacturing presence and specialty-product capabilities support differentiation. Continued development of higher-value vinyl materials, operational efficiency, and improved resource utilization could create opportunities as sustainability requirements become more stringent.
- Orbia Advance Corporation
Orbia participates in the PVC value chain through its Vestolit business and in PVC-based infrastructure solutions through its broader operations. In August 2025, Orbia completed the sale of its Wavin pipes and fittings business in India to Supreme Industries for USD 30 million, subject to working-capital adjustments, alongside a long-term technology licensing agreement. The transaction demonstrates how technology licensing and strategic portfolio changes can extend access to advanced water-management solutions and reshape competitive opportunities in infrastructure-related PVC applications.
Other significant industry participants include Occidental Petroleum Corporation, Olin Corporation, Hanwha Solutions, and Vynova Group.
Regional Analysis: Key Countries
China: China is a major global PVC production and consumption center, supported by extensive chemical manufacturing, construction activity, and infrastructure requirements. Demand is influenced by residential development, water-management projects, electrical applications, and industrial production. Government priorities involving urban infrastructure, energy efficiency, and pollution control shape the industry's operating environment. However, property-sector weakness, manufacturing overcapacity, and environmental compliance costs can affect consumption and profitability.
United States: The US market benefits from water infrastructure modernization, residential construction, electrical networks, and industrial investment. Federal infrastructure funding, including programs established under the Infrastructure Investment and Jobs Act, supports eligible water and public-utility projects. These investments can increase demand for PVC pipes, conduits, and related products. Feedstock economics, housing activity, and environmental regulation remain important influences on growth.
Germany: Germany's PVC demand is closely connected to construction, building renovation, automotive manufacturing, and electrical equipment. Energy-efficient building upgrades and infrastructure modernization create opportunities for durable PVC profiles, pipes, and insulation materials. European chemical regulations, recycling requirements, and circular-economy initiatives are also encouraging manufacturers to improve material recovery and product sustainability.
United Kingdom: The UK market is supported by housing development, water infrastructure improvements, building renovation, and electrical installations. Government housing objectives and investment in water networks provide potential demand opportunities. Building standards, waste-management policies, and sustainability requirements are encouraging greater attention to product durability and responsible material disposal.
France: France's market benefits from construction renovation, public infrastructure, water distribution, and electrical applications. Energy-efficiency programs and building modernization support demand for durable construction materials. European chemical safety and circular-economy frameworks also influence manufacturers' product development and recycling strategies.
Japan: Japan's PVC market is supported by infrastructure maintenance, urban redevelopment, plumbing systems, and industrial applications. Investment in resilient infrastructure and the replacement of aging water networks creates opportunities for durable piping solutions. Demographic pressures and relatively mature construction demand, however, can limit expansion in some applications.
Country-specific PVC market-share percentages are not stated here because the referenced market report's publicly available summary does not establish comparable shares for these individual countries.
Key Players
- Shin-Etsu Chemical Co., Ltd.
- Westlake Corporation
- Formosa Plastics Corporation
- INEOS Group
- Orbia Advance Corporation
- Occidental Petroleum Corporation
- Olin Corporation
- Hanwha Solutions Corporation
- Vynova Group
Why This Market Matters Now
The PVC market matters because reliable water infrastructure, affordable construction, electrical safety, and industrial development depend on cost-effective, durable materials. With global revenue projected to reach USD 94.02 billion by 2032, manufacturers have opportunities to expand production efficiency, develop specialized formulations, improve recycling systems, and respond to evolving sustainability expectations. Businesses that balance competitive pricing with innovation, regulatory compliance, and responsible material management will be better positioned to capture long-term demand.
Explore More Related Reports
Agricultural Films Market https://www.maximizemarketresearch.com/market-report/agricultural-films-market-global/42869/
Global Carbon thermoplastic market https://www.maximizemarketresearch.com/market-report/global-carbon-thermoplastic-market/82551/
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company providing data-focused business insights across healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, and strategic consulting, MMR helps organizations understand market conditions, identify opportunities, and make informed business decisions.
Contact Us
Maximize Market Research Pvt. Ltd.
2nd Floor, Navale IT Park Phase 3
Pune Bangalore Highway, Narhe
Pune, Maharashtra 411041, India
Phone: +91 9607365656
Email: sales@maximizemarketresearch.com