Redefining Credit Scoring and Loan Underwriting Models Using Generative AI to Enhance Financial Inclusion and Accuracy
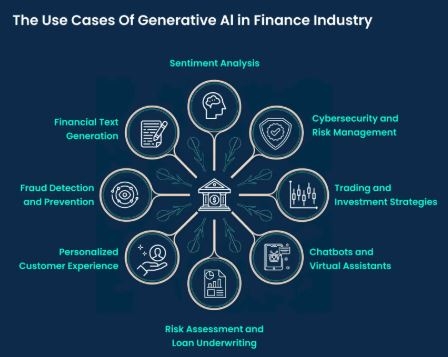
Traditional credit scoring models have long relied on limited datasets, often excluding individuals with "thin" credit files from the formal economy. However, the Generative AI In Fintech Market growth is fundamentally changing this dynamic by allowing lenders to incorporate non-traditional data points into their assessments. Generative models can analyze a borrower's cash flow patterns, utility payments, and even educational background to generate a more comprehensive risk profile. This enables financial institutions to extend credit to underserved populations while maintaining, or even improving, the health of their loan portfolios. By moving away from rigid, legacy scoring systems, the fintech industry is fostering a more inclusive environment where creditworthiness is determined by a holistic view of an individual's financial behavior rather than a single, often flawed, numerical score.
The implementation of AI in underwriting also speeds up the loan approval process from days to seconds. This immediacy is crucial in the modern economy, where small businesses often require quick access to capital to seize growth opportunities. Generative AI can automatically verify documents, cross-reference data across multiple platforms, and flag potential inconsistencies for human review, significantly reducing the likelihood of manual error or fraud. As these models continue to learn from new data, they become increasingly adept at predicting defaults and managing risk during economic downturns. The challenge lies in ensuring these models remain transparent and explainable to regulators, as the "black box" nature of some AI algorithms can raise concerns about fairness and accountability. Addressing these challenges head-on will be essential for the widespread adoption of AI-driven lending.
FAQs How does AI help people with no credit history? It uses alternative data like rent payments and transaction history to build a "synthetic" credit profile that proves reliability to lenders.
Does AI-driven underwriting increase the risk of bank failure? On the contrary, AI can provide more accurate risk assessments and stress-testing, potentially making the banking system more stable by identifying bad loans earlier.
➤➤➤Explore MRFR’s Related Ongoing Coverage In Semiconductor Industry:
Solid State Power Amplifier Market
Debt Collection Software Market